2026 Housing Market Forecast: Rates & Affordability for First-Time Buyers
Anúncios
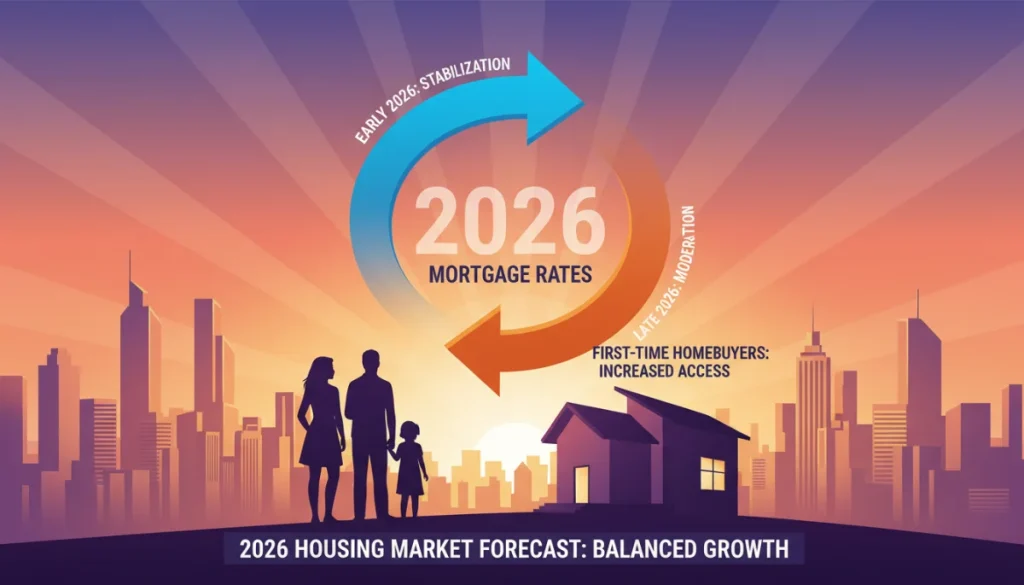
The 2026 housing market forecast suggests a period of stabilization with potential for moderate appreciation, influenced by recalibrated mortgage rates and ongoing efforts to address affordability for first-time buyers.
As we approach 2026, the question on many minds, especially those dreaming of homeownership, is what the future holds for the real estate landscape. The 2026 housing market forecast is poised to be a pivotal year, characterized by intricate shifts in mortgage rate trends and persistent, yet evolving, challenges concerning affordability for first-time buyers across the United States. Understanding these dynamics is crucial for anyone looking to enter or navigate the housing market effectively.
Anúncios
Understanding the Current Housing Market Dynamics
The housing market is a complex ecosystem, constantly influenced by a myriad of economic indicators, demographic shifts, and policy decisions. Before delving into the 2026 projections, it’s essential to grasp the forces currently shaping the market. Recent years have seen unprecedented fluctuations, from record-low interest rates fueling a buying frenzy to subsequent increases that have cooled demand and intensified affordability concerns. These rapid changes have created a landscape where careful analysis and strategic planning are paramount for both buyers and sellers.
Economic stability, employment rates, and inflation all play significant roles in the health of the housing market. A strong job market typically translates to higher demand for housing, while inflationary pressures can lead to increased interest rates, making homeownership more expensive. The interplay of these factors creates a dynamic environment that requires continuous monitoring and adaptation. Understanding the current state provides a crucial foundation for anticipating future trends and preparing for what lies ahead.
Anúncios
Key Economic Indicators Influencing Housing
Several economic indicators are particularly influential in shaping the housing market. These metrics offer insights into the broader economic health and directly impact consumer purchasing power and lender behavior. Keeping an eye on these indicators can help prospective buyers and sellers make more informed decisions.
- Inflation Rates: Persistent inflation often prompts central banks to raise interest rates, directly affecting mortgage costs.
- Employment Figures: Robust job growth and low unemployment typically boost consumer confidence and housing demand.
- GDP Growth: A healthy Gross Domestic Product (GDP) indicates a strong economy, generally supporting a stable housing market.
- Consumer Confidence: High consumer confidence encourages major purchases like homes, while low confidence can lead to market stagnation.
The current housing market is a culmination of these forces, reflecting a period of adjustment and recalibration. As we move towards 2026, these same indicators will continue to be critical in determining the market’s trajectory. The lessons learned from recent volatility will undoubtedly inform future strategies for all participants.
Mortgage Rate Trends: What to Expect in 2026
Mortgage rates are arguably the most critical factor influencing housing affordability and buyer activity. The trajectory of these rates in 2026 will heavily dictate the accessibility of homeownership, particularly for first-time buyers. While predicting exact figures is challenging, economic forecasts suggest a potential stabilization or even a slight decline from recent peaks, though unlikely to return to the ultra-low levels seen during the pandemic. This anticipated shift could offer a much-needed reprieve for those currently priced out of the market.
Central bank policies, global economic conditions, and domestic inflation continue to be the primary drivers of mortgage rates. As inflation moderates and economic growth stabilizes, there may be less pressure on central banks to maintain aggressive rate hikes. This could lead to a more predictable and potentially more favorable lending environment, allowing buyers to plan their finances with greater certainty. However, unexpected economic shocks could still introduce volatility, making flexibility and preparedness key.
Factors Influencing Mortgage Rate Movements
Understanding the underlying factors that cause mortgage rates to fluctuate is essential for anticipating future trends. These elements are interconnected and can create a ripple effect throughout the financial system, ultimately impacting the cost of borrowing for a home.
- Federal Reserve Policy: The Fed’s decisions on the federal funds rate directly influence short-term interest rates, which in turn affect long-term mortgage rates.
- Inflation Expectations: Lenders incorporate future inflation expectations into their rates; higher expected inflation usually means higher mortgage rates.
- Bond Market Performance: Mortgage rates are closely tied to the yield on U.S. Treasury bonds. When bond yields rise, so do mortgage rates.
- Economic Growth: Strong economic growth can lead to higher demand for credit, pushing interest rates upwards.
For 2026, many experts project a more tempered approach from central banks, assuming inflation remains under control. This could translate into a more stable, albeit still elevated, mortgage rate environment compared to the extremes of previous years. Buyers should remain vigilant, as even small shifts can significantly impact monthly payments and overall affordability.
Affordability Challenges for First-Time Buyers
Affordability remains a significant hurdle for many aspiring homeowners, especially first-time buyers. High home prices, coupled with elevated mortgage rates, have created a challenging entry point into the market. While some relief in mortgage rates is anticipated, the fundamental issue of housing supply and demand continues to exert upward pressure on prices in many desirable areas. This creates a dual challenge where even with slightly lower rates, the sheer cost of a home can still be prohibitive.
First-time buyers often lack the substantial equity that existing homeowners can leverage, making down payments and closing costs particularly burdensome. The struggle is further compounded by rising living expenses and student loan debt, which can limit savings potential. Addressing these multifaceted affordability issues will require a combination of market adjustments, innovative financial products, and potentially governmental support programs designed to ease the path to homeownership.
Strategies to Overcome Affordability Barriers
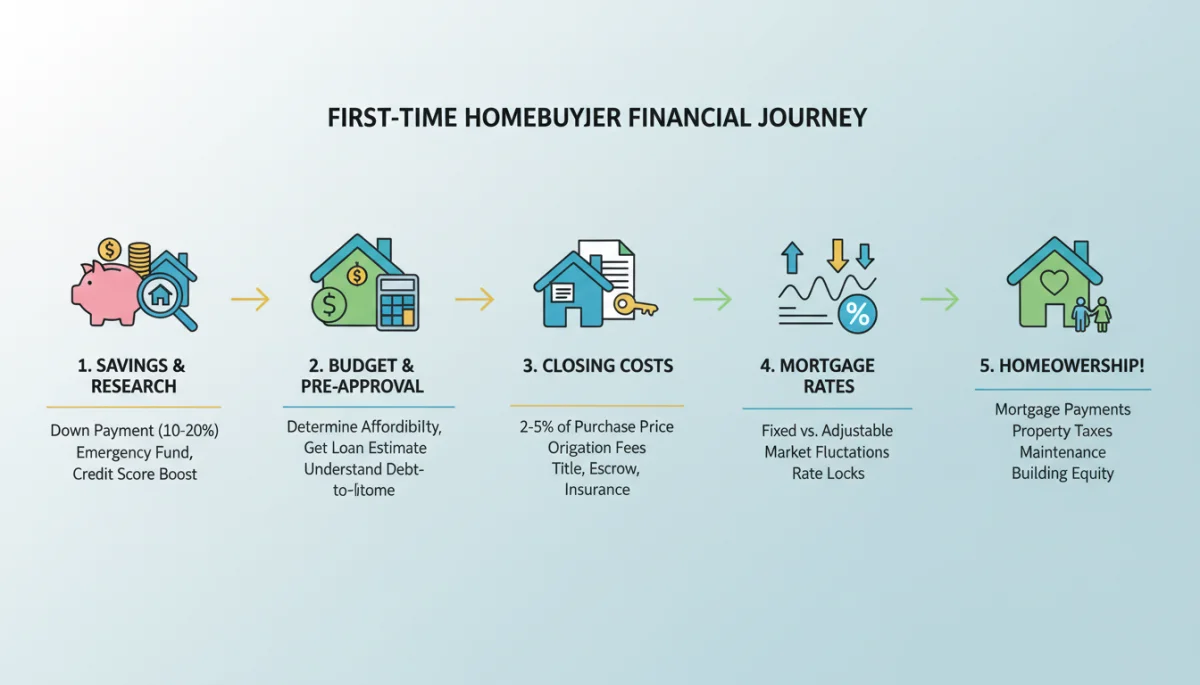
Despite the challenges, there are various strategies first-time buyers can employ to improve their chances of homeownership. Proactive planning and exploring available resources can make a substantial difference in navigating the current market.
- Saving for a Down Payment: Prioritizing consistent savings and exploring high-yield savings accounts can accelerate down payment accumulation.
- Improving Credit Score: A strong credit score can unlock better mortgage rates and more favorable loan terms.
- Exploring Down Payment Assistance Programs: Many state and local programs offer grants or low-interest loans to help with down payments and closing costs.
- Considering FHA/VA Loans: These government-backed loans often have lower down payment requirements and more flexible credit criteria.
The path to homeownership for first-time buyers in 2026 will likely still require dedication and strategic financial planning. However, with potential shifts in mortgage rates and continued development of supportive programs, the outlook could become incrementally more favorable than in recent years.
Regional Variations in the 2026 Housing Market
The United States housing market is not a monolith; rather, it is a collection of diverse regional markets, each with its unique characteristics and drivers. What holds true for a bustling metropolitan area might be entirely different for a rural community or a rapidly growing sunbelt city. In 2026, these regional variations are expected to persist, with some areas experiencing continued robust demand and price appreciation, while others may see more moderate growth or even slight corrections. Factors such as local job markets, population migration patterns, and housing supply levels will continue to play a crucial role in these localized trends.
Understanding these regional nuances is vital for both buyers and investors. A national forecast provides a general overview, but a deeper dive into specific geographical areas reveals a more accurate picture of potential opportunities and challenges. For example, areas with strong tech industries might continue to see high demand, while regions facing economic slowdowns could experience a cooling off. These localized dynamics necessitate tailored strategies for anyone looking to make a move in the 2026 housing market.
Hotspots and Cooling Markets in 2026
Certain regions are projected to remain highly competitive, while others might offer more buyer-friendly conditions. These differences are often tied to specific economic drivers and demographic shifts.
- Growth Markets: Cities with strong job creation, particularly in high-wage sectors, and robust population influx are likely to maintain strong demand and price growth.
- Stable Markets: Established markets with balanced supply and demand may see steady, moderate appreciation, offering predictable investment opportunities.
- Cooling Markets: Areas that experienced rapid, unsustainable price surges might see a flattening or slight decrease in prices as demand adjusts to higher rates.
For potential homeowners, researching specific local markets is paramount. What constitutes a good investment or an affordable entry point can vary drastically depending on the region. The 2026 housing market will continue to reflect this patchwork of local conditions, emphasizing the importance of localized market intelligence.
The Role of Housing Supply and Construction
The persistent shortage of housing supply has been a significant contributor to rising home prices in recent years, exacerbating affordability issues. As we look towards 2026, the pace of new construction will be a critical factor in determining whether this supply-demand imbalance can begin to normalize. While construction activity has increased in some areas, it often struggles to keep pace with population growth and household formation, especially in high-demand regions. Labor shortages, rising material costs, and regulatory hurdles continue to challenge builders, slowing down the rate at which new homes can be brought to market.
A sustained increase in housing starts and completions would be beneficial for the market, potentially easing price pressures and offering more options for buyers. However, achieving this balance is a long-term endeavor. Policy makers and industry stakeholders are exploring various solutions, from streamlining permitting processes to promoting innovative construction techniques, all aimed at boosting supply. The success of these efforts will have a tangible impact on the 2026 housing market forecast and its long-term health.
Impact of Construction on Market Balance
New construction plays a vital role in restoring equilibrium to the housing market. Its influence extends beyond simply adding units; it also affects pricing, competition, and overall market stability.
- Increased Inventory: More new homes provide buyers with greater choice, potentially reducing bidding wars and moderating price growth.
- Diverse Housing Options: New developments can introduce a variety of housing types, from single-family homes to townhouses and condos, catering to different buyer needs and budgets.
- Economic Stimulus: Construction activity generates jobs and stimulates local economies, contributing to overall economic health.
- Addressing Population Growth: Sufficient new housing is essential to accommodate growing populations and prevent severe housing shortages.
The pace of construction in the coming years will be a key determinant of whether the housing market can achieve a healthier balance between supply and demand. While challenges remain, any significant uptick in new home building would be a positive sign for the 2026 housing market and beyond.
Government Policies and Their Impact on the Market
Government policies at federal, state, and local levels wield considerable influence over the housing market. These policies can affect everything from mortgage availability and affordability to land use and new construction. In the lead-up to 2026, we can expect continued discussions and potential implementations of policies aimed at addressing housing challenges, particularly for first-time buyers. This includes initiatives related to down payment assistance, zoning reform, and affordable housing development. The effectiveness of these policies will play a crucial role in shaping the market’s trajectory and ensuring equitable access to homeownership.
For instance, changes in tax credits for homebuyers, adjustments to FHA loan requirements, or new infrastructure spending can all have significant ripple effects. Local zoning laws, which dictate what can be built where, directly impact housing density and supply. As the housing market continues to evolve, the interplay between economic forces and governmental intervention will be a critical area to watch. These policies often aim to counteract market imbalances, making them an integral part of any comprehensive housing market forecast.
Key Policy Areas to Monitor
Several policy areas are particularly relevant to the housing market and could see developments impacting the 2026 outlook. Staying informed about these potential changes is important for stakeholders.
- Affordable Housing Initiatives: Programs designed to create or preserve affordable housing units, often through subsidies or incentives for developers.
- First-Time Buyer Assistance: Federal and state programs offering grants, tax credits, or favorable loan terms to help first-time homebuyers.
- Zoning and Land Use Reform: Efforts to relax restrictive zoning laws to allow for more diverse housing types and higher density, potentially increasing supply.
- Mortgage Market Regulations: Changes in how mortgages are underwritten, insured, or serviced, which can affect lending standards and accessibility.
The impact of government policies on the 2026 housing market cannot be overstated. From stimulating construction to providing direct financial aid, these interventions will be crucial in attempting to navigate the complex challenges of affordability and supply, ultimately influencing the opportunities available to prospective homeowners.
Preparing for the 2026 Housing Market: Advice for Buyers
For prospective buyers, especially first-timers, preparing for the 2026 housing market forecast requires a proactive and informed approach. While the market may offer some stabilization compared to recent years, it will still demand strategic planning and financial readiness. The goal is to position oneself advantageously to capitalize on potential opportunities while mitigating risks associated with fluctuating rates and persistent affordability challenges. This preparation involves more than just saving; it encompasses understanding the market, assessing personal finances, and exploring all available resources.
Embarking on the homeownership journey in 2026 means being adaptable and diligent. Market conditions can shift, and being well-prepared ensures that you can react effectively to new developments. Whether it’s locking in a favorable mortgage rate or finding the right down payment assistance program, informed decisions will be your greatest asset. The housing market is a significant investment, and thorough preparation is the cornerstone of a successful purchase.
Essential Steps for Prospective Homebuyers
Taking concrete steps now can significantly improve your position when the time comes to buy a home in 2026. These actions cover financial readiness, market understanding, and leveraging expert advice.
- Get Pre-Approved for a Mortgage: Understanding your borrowing capacity early helps narrow down your search and makes your offer more attractive.
- Build a Strong Financial Foundation: Focus on reducing debt, increasing savings, and maintaining a healthy credit score.
- Research Local Markets Thoroughly: Understand price trends, inventory levels, and neighborhood specifics in your target areas.
- Work with Experienced Professionals: A knowledgeable real estate agent and mortgage broker can provide invaluable guidance and access to resources.
By taking these preparatory steps, first-time buyers can approach the 2026 housing market with confidence, ready to navigate its complexities and achieve their dream of homeownership. The landscape may be challenging, but with the right strategy, it is certainly navigable.
| Key Point | Brief Description |
|---|---|
| Mortgage Rate Outlook | Expect potential stabilization or slight decline from recent peaks, driven by central bank policies and inflation trends. |
| Affordability Challenges | High home prices and closing costs remain significant barriers for first-time buyers, requiring strategic financial planning. |
| Regional Market Diversity | Performance will vary significantly by region, influenced by local job markets, population shifts, and housing supply. |
| Supply and Policy Impact | Increased construction and government policies will be crucial in addressing supply shortages and enhancing affordability. |
Frequently Asked Questions About the 2026 Housing Market
While a significant drop to pre-pandemic lows is unlikely, experts anticipate a potential stabilization or slight decline from current peaks. This would be driven by moderating inflation and central bank policies aiming for economic stability, offering some relief to buyers.
The primary challenges include high home prices, accumulating sufficient down payments, and navigating closing costs. While mortgage rates may ease, the overall cost of homeownership remains a significant hurdle, requiring diligent saving and financial planning.
Housing supply will continue to be a critical factor. Increased new construction could help alleviate price pressures and provide more options. However, persistent shortages, particularly in high-demand areas, may sustain competitive conditions and upward price trends.
Yes, various federal, state, and local programs are expected to remain available. These include FHA and VA loans with lower down payment requirements, as well as down payment assistance grants and low-interest loans. Researching these options is highly recommended.
The decision to buy depends on individual financial situations and local market conditions. While some stabilization is anticipated, significant price drops are not widely forecast. Consulting with a financial advisor and real estate professional can help determine the best timing for your specific circumstances.
Conclusion
The 2026 housing market forecast presents a nuanced picture, characterized by evolving mortgage rate trends and ongoing affordability challenges, especially for first-time buyers. While a complete return to past market conditions is unlikely, the anticipation of stabilizing interest rates and continued efforts to boost housing supply offer a glimmer of hope. Success in this market will hinge on thorough preparation, strategic financial planning, and a keen understanding of regional dynamics. For those aspiring to homeownership, staying informed and proactive will be paramount in navigating the complexities and seizing opportunities that emerge in the coming years.
